September 29, 2017
We are proud to provide these significant benefit improvements. In addition to prior cost of living increases for our retired and deferred members, these measures add to our members’ financial security in retirement.
These changes take effect Jan. 1, 2018. The details of the three changes, including who they apply to, are set out below.
What if I’ve already made the decision to retire or I leave my employer before Jan. 1, 2018?
If you are an active member but have made a decision to start your pension on or after Oct. 1, 2017, these changes will be applied to you. If you are eligible to retire, your last day of work is on or after Oct. 1, 2017, and you defer your pension, these changes will be applied to you. HOOPP will contact you with more details.
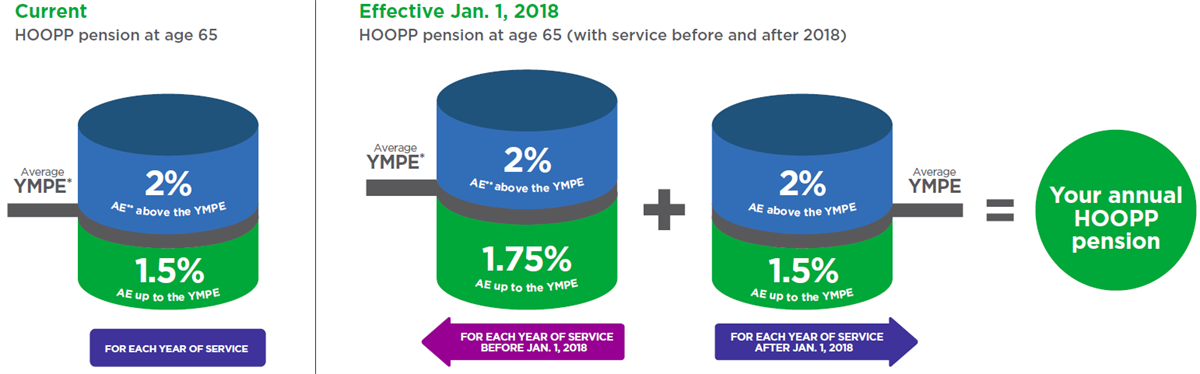
*Average YMPE = year’s maximum pensionable earnings
**AE = Average earnings
This case study shows the impact of this improvement on a member’s pension:
Meet Jennifer, HOOPP member since Jan. 1, 2008.
Jennifer works full-time and has annual average earnings of $60,000 at retirement.
She will retire at age 65 on Jan. 1, 2028 with:
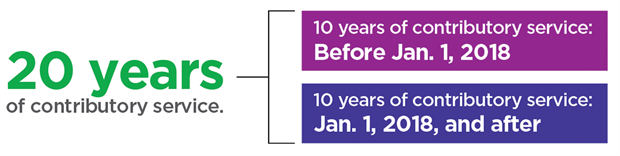
The figures below show how her pension benefit increases as a result of this improvement.
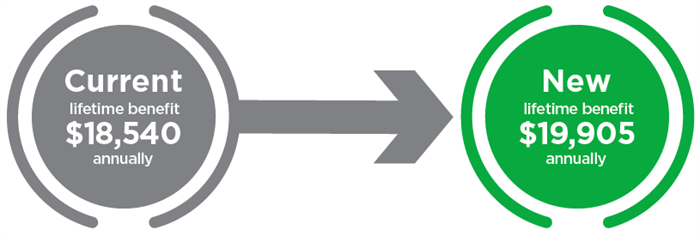
*This simple example assumes that the average YMPE at Dec. 31, 2027 is equal to the average YMPE at Dec. 31, 2017.
*This example and calculation are for illustrative purposes only. Your annual pension will differ from this example due to the assumptions in this example and your personal circumstances. For this reason, you should not rely on the example for decision-making purposes.
This change increases your lifetime pension. When you retire between the ages of 55 and 65, you receive both a bridge benefit and a lifetime pension. Before age 65, your total benefit from HOOPP will remain the same because your bridge benefit is being adjusted to reflect the increase in your lifetime pension.
The lifetime pension you will receive from HOOPP when you turn age 65 will be higher than it would have been prior to this change. You will receive this benefit for the rest of your life.
As a result of this benefit improvement, you will receive a past service pension adjustment (PSPA) from HOOPP in 2018. A PSPA is used to show an increase in the value of your past pension service and it will decrease your available registered retirement savings plan (RRSP) contribution room.
To calculate your pension, we currently use the average YMPE for the three calendar years immediately before your retirement. The YMPE is an amount set each year by the federal government based on the average wage in Canada.
Starting Jan. 1, 2018, we will use the average YMPE for the five calendar years immediately before your retirement to calculate your pension. Since this average will be lower, more of your pension may be paid out at the 2% rate.
This benefit applies to active members (not retired or deferred) on or after Jan. 1, 2018.
This improvement consists of two parts:
An increase to the minimum survivor benefit for your qualifying spouse when you pass away in retirement, and
A new five-year guarantee from your retirement date for survivor benefits for your qualifying spouse.
Together, these changes provide added financial security for you and your loved ones.
This improvement applies to retired members, and active or deferred members who retire on or after Jan. 1, 2018.
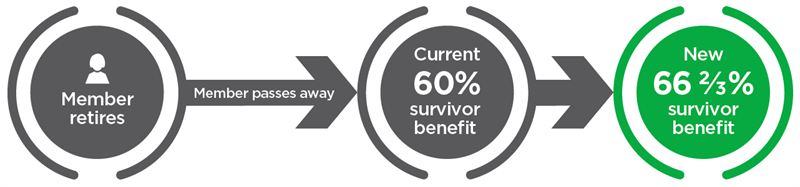
When you pass away in retirement, your spouse at the time of your retirement is entitled to receive 60% of your monthly pension, not including a bridge benefit, for the rest of his or her life. When you retire, you may choose to increase this benefit to 80% or 100% of your monthly pension. These options will result in a reduction in your pension to reflect the additional benefit for your spouse.
Increase to the minimum survivor benefit
The minimum survivor benefit to your spouse is increasing to 66 2/3% of your monthly benefit, up from 60%, payable for the rest of his or her life.
Five-year guarantee period
If you pass away within five years of your retirement date, your surviving spouse will receive the same monthly benefit as you (not including the bridge benefit) for the rest of the five-year period. When the five-year period ends, your spouse will receive 66 2/3%, 80%, or 100% of your monthly benefit, depending on your choice at retirement. If both you and your spouse pass away before the end of the five-year period, the remaining payment will go to your beneficiary(s) or, if there are none, to your estate.
The following example shows the impact of this benefit improvement.
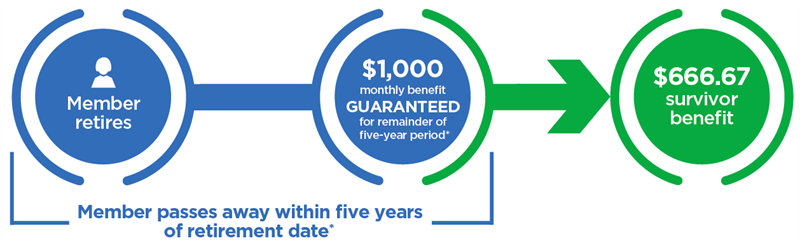
*If you have a spouse at retirement, your monthly benefit is guaranteed for the five-year period after your retirement date.
Shalini is a HOOPP member whose pension benefit is $1,000 per month. She passes away two years after retiring. Her spouse will continue to receive $1,000 per month for three years, then receive a monthly survivor benefit of $666.67, or two-thirds of Shalini's monthly pension, for the rest of his life.
If you don’t have a spouse at retirement, payment of your monthly benefit is already guaranteed for a period of 15 years, the maximum benefit permitted under the Income Tax Act.
HOOPP is proud to make these significant improvements to our Plan so we can provide our members and their loved ones with added financial security in retirement.
We're here to help!
For more information, please call HOOPP Member Services at 416-646-6445 or toll-free in Canada and the U.S. at 1-877-43HOOPP (46677), Monday through Friday, 8 a.m. to 5 p.m., Eastern Time.