Meet Mariella
See how her contributions would change if she worked full time vs. part time.
HOOPP makes building financial security for your future easy. The amount you contribute to your pension is based on your earnings and HOOPP’s contribution rates. Here’s how it works.
Each pay period, your employer calculates your contributions and deducts them directly from your pay. Your employer also helps support your retirement security — for every dollar that you contribute, your employer adds $1.26.
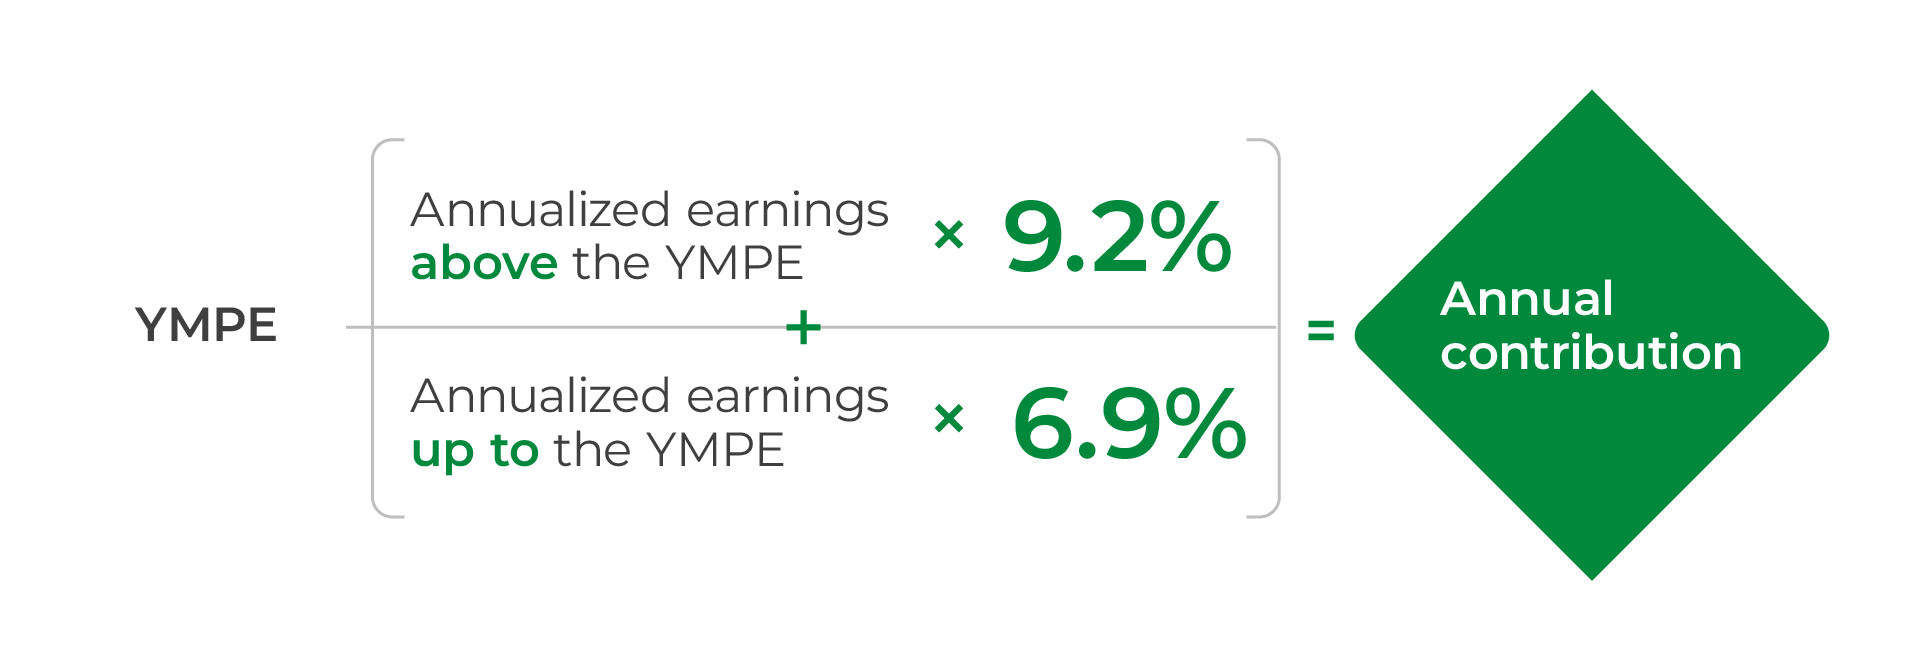
Here’s what you currently contribute:
6.9% of your earnings up to the year's maximum pensionable earnings (YMPE)
9.2% of your earnings above the YMPE
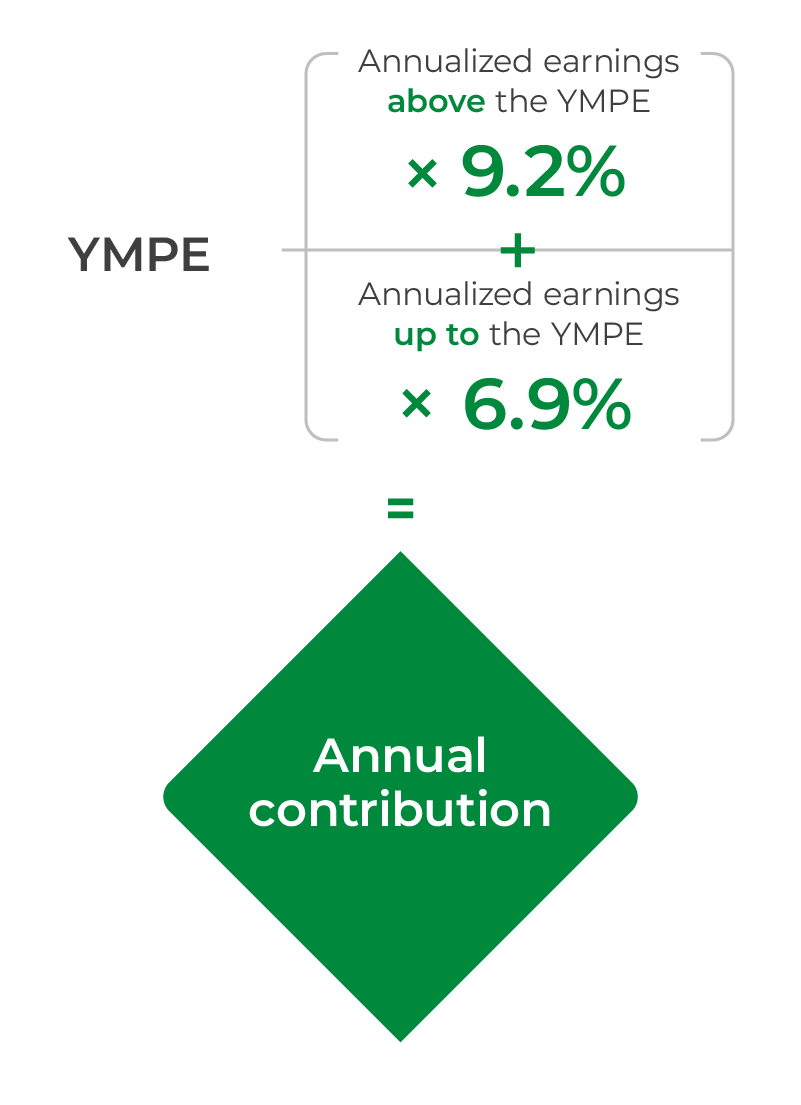
YMPE stands for year’s maximum pensionable earnings. It’s an amount set each year by the Canadian government based on the average wage in Canada. At HOOPP, you contribute at different rates on your annualized earnings up to and above the YMPE.
In 2026, the YMPE is $74,600.
If you don’t work full-time hours in your position, your contributions will be based on what you would have earned working full-time hours. Your contributions will then be adjusted according to the percentage of full-time hours you work.
See how her contributions would change if she worked full time vs. part time.
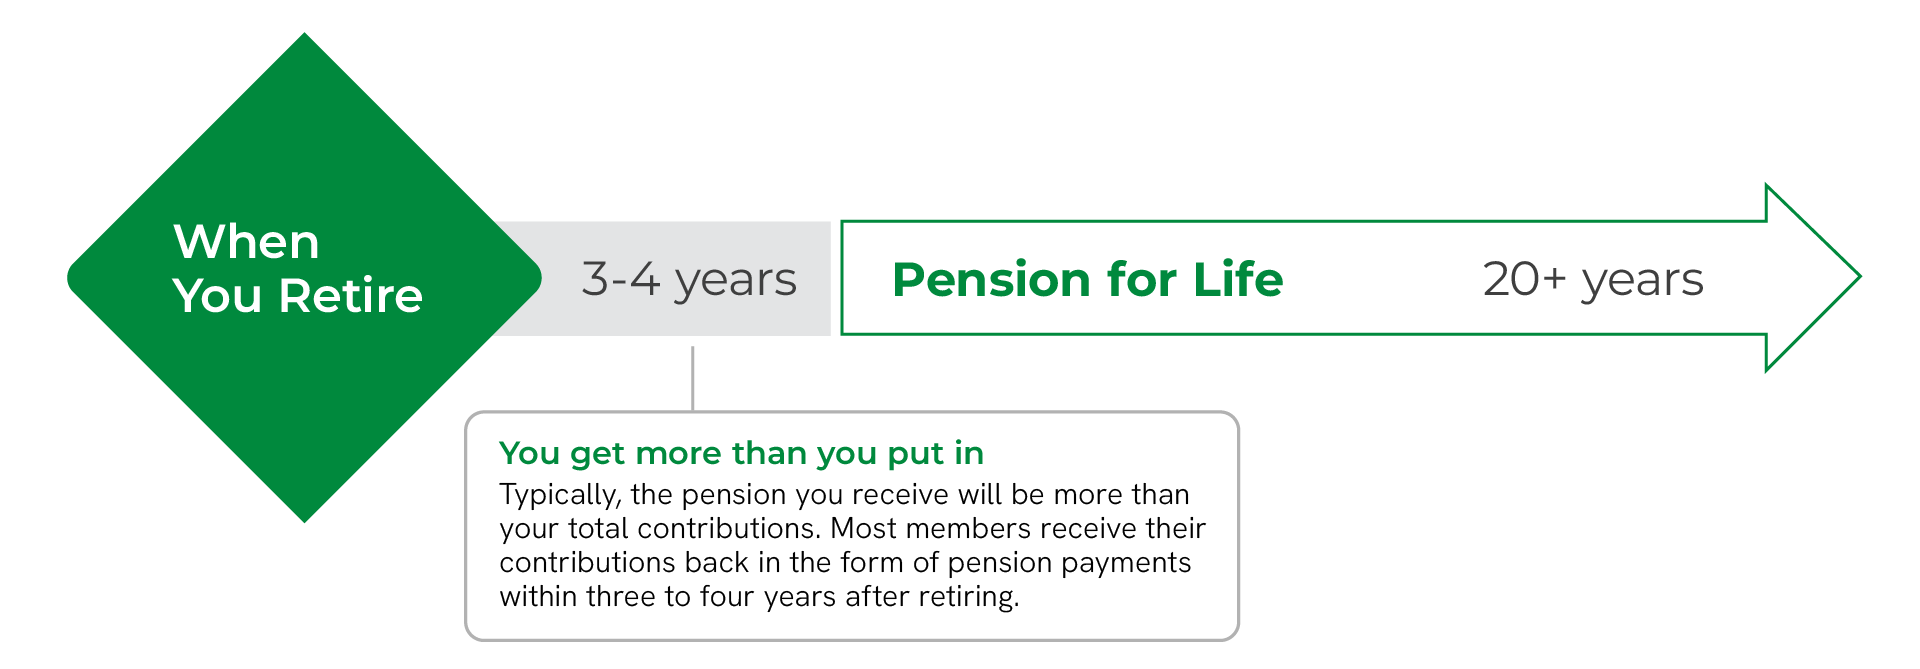
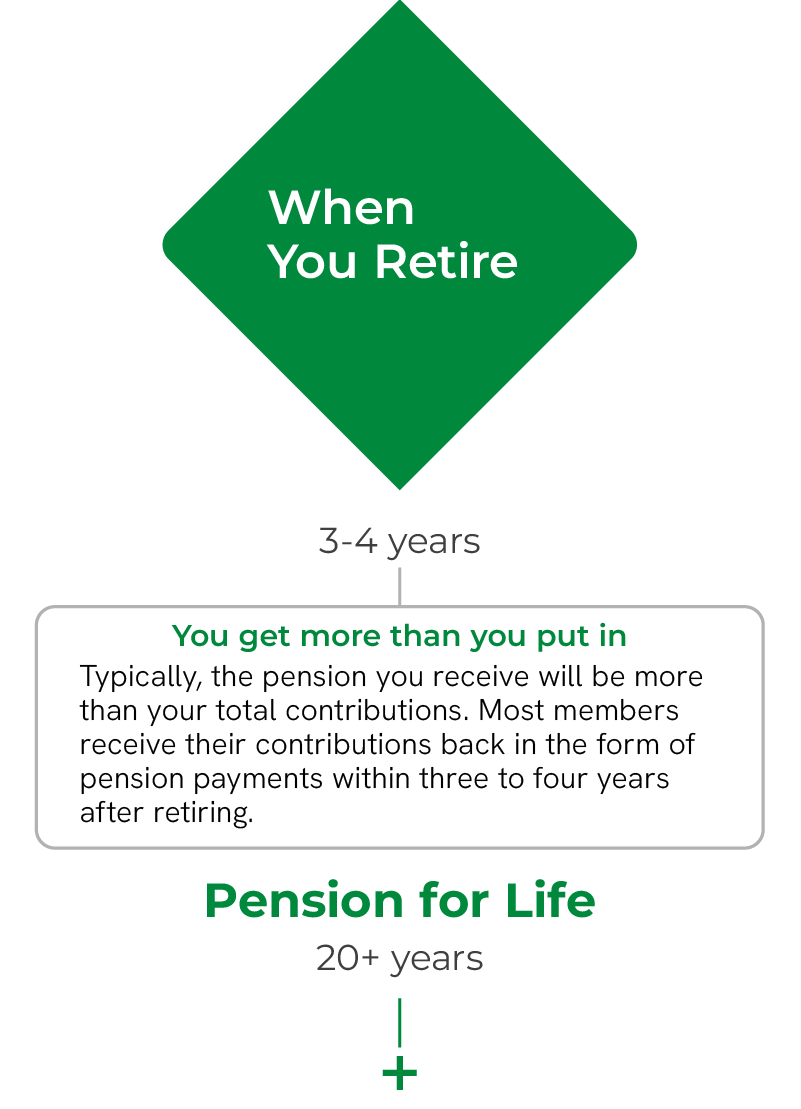
The pension you receive over a span of 20+ years is much more than your total contributions. In fact, after three to four years of retirement, most members have already received more in pension payments than they contributed over their whole career.
Your contributions are invested in the HOOPP Fund, which is managed by our in-house team of investment professionals. For every pension dollar you receive in retirement, 70 cents comes from investment returns and only 30 cents comes from member and employer contributions.
Plus, you may also benefit from features such as survivor benefits and inflation protection that can increase value of your pension even more.
Did you know that your regular contributions to your HOOPP pension reduce your taxable income?
At tax time, your pension contributions are reported on your T4 tax slip. Since your pension contributions are made through payroll deductions before taxes are deducted, you don’t pay tax on that portion of your salary.
Did you know that compared to some of the larger Canadian pension plans, HOOPP contribution rates are among the lowest? Plus, they have not changed since 2004. That’s more than 20 years!
The HOOPP Board of Trustees sets these rates and can adjust them. Every year, the Board reviews and decides whether to maintain current rates.