There are times when you may need to be away from work, perhaps because you’re having a baby, or you need to tend to a personal emergency.
In many cases where your employer has approved your leave from work, you can continue to build your HOOPP pension by making contributions for your leave of absence. In fact, making contributions will help you build your pension over the long run.
Starting in 2027, some of the most common leaves will automatically be included in your HOOPP eligibility service, at no cost to you or your employer. This applies to any portion of your leave that occurs in 2027 or later. If you are already on such a leave, this applies to the portion on and after January 1, 2027.
This means if you are away from work on a statutory leave, a health leave or because of a strike or lockout, you will continue to receive eligibility service, even if you don’t contribute during that period.
Eligibility service is the length of time you have been a member of HOOPP and is used to calculate any adjustment to your pension if you decide to retire early. This change can help you to qualify for a higher early retirement pension or to reach your early retirement date sooner, even if you don’t make contributions for your eligible leave.
As outlined in the Ontario Employment Standards Act (ESA), you can choose to make contributions for the following types of leaves:
Pregnancy leave
Parental leave
Family medical leave
Emergency leave
Organ donor leave
Family caregiver leave
Critically ill child care leave
Crime-related child death and disappearance leave
Your employer may grant other types of leaves, for example, for travel or education. If your employer approves a leave that lasts less than 31 days, contributions are mandatory for you and your employer. If your employer approves a leave that is 31 days or more, your employer decides whether you can make contributions. If you are permitted to contribute and do so, your employer must contribute as well.
If you are unable to work due to physical or mental illness, or injury, your employer may place you on a health leave. This is handled differently from other types of leaves. Learn more about how you can contribute during the first 15 weeks of a health leave.
Strikes or lockouts. You can choose whether to contribute for a period of strike or lockout.
Temporary period of reduced earnings. If your employer permits, you can choose to “top up” your contributions during a temporary period of reduced earnings, as long as you have been with the same employer for at least three months. Examples of a temporary period of reduced earnings include: participating in a temporary job-sharing program or working fewer hours each week for a temporary period of time.
Temporary layoffs. For layoffs less than 31 days, you and your employer continue to make contributions. For layoffs longer than 30 days, your employer determines if contributions continue.
Pre-paid leave plans. For example, a four-for-five arrangement allows employees to receive 80% of their earnings for four years while “banking” the remaining 20% of their earnings to take as income during the fifth year which is taken as a year off.
For the first four years, contributions are based on 100% of your earnings, even though you are only receiving 80% of their normal earnings during this time. This means you will accrue full contributory service during the first four years, just as you would if you were not taking a leave in the fifth year. Your employer will also make contributions based on your full earnings.
There are two ways in which you can build pension service for the fifth year, while you are away from work: you can make contributions or you can buy back this period. Contributions are based on 100% of what you would have earned had you worked your usual hours.
According to Canadian tax rules, there are restrictions on the total contributory service you can build while away from work on a leave from a HOOPP employer. This applies to all statutory and non-statutory leaves, strikes or lockouts, temporary period of reduced earnings and pre-paid leave plans.
Note that these restrictions do not apply to health leaves or any eligible periods that you purchase on a past service basis.
If you are absent from work that is not an employer-approved leave — for example you are placed on a suspension or do not have permission to take time off work — and your absence is not due to other circumstances as noted above contributions are not permitted for this period. As a result, you will not receive contributory service for this period and will not be eligible to buy back this period.
If you are away from work for other reasons, contact Member Services or your employer to determine if you can elect to continue your contributions.
If you decide to make contributions during a statutory leave or are permitted to do so during a non-statutory leave, there are two ways you can contribute:
Contribute while you’re away, as though you were working, or
Pay the lump sum of your contributions no later than six months from the end of your leave
Speak with your employer to make arrangements regarding your contributions.
If you work full-time
Your contributions are based on your full pre-leave earnings, though you can contribute less. The more you contribute, the more service and earnings you’re building for your pension in retirement.
If you work part-time
Your contributions for the leave period will be based on your average hours worked prior to the leave.
It’s in your best interest to make these contributions as soon as possible. If you delay making contributions following the end of your leave, HOOPP may be required to report a Past Service Pension Adjustment (PSPA) to the Canada Revenue Agency (CRA). The CRA will reduce your available RRSP contribution room by the amount of the PSPA and must certify the PSPA before your leave period can be recognized by HOOPP. If CRA does not certify the PSPA, please contact our Member Services team to discuss your options.
Contributing for a leave of absence prevents a gap in your service and ensures that you will have more years of contributory service at retirement. That can make a big difference in your pension benefit when it’s time to retire.
Here’s a simple example:
Lucia and Michelle are the same age and were hired at the same hospital on the same day. They both earn an average of $85,000 per year. Lucia and Michelle both decide to retire on January 1, 2026. Both have two children and both took two eighteen month pregnancy/parental leaves. Lucia made contributions for both of her leaves, but Michelle did not.
That means Lucia has 17 years of contributory and eligibility service and Michelle has 14 years when they each retire at age 55.
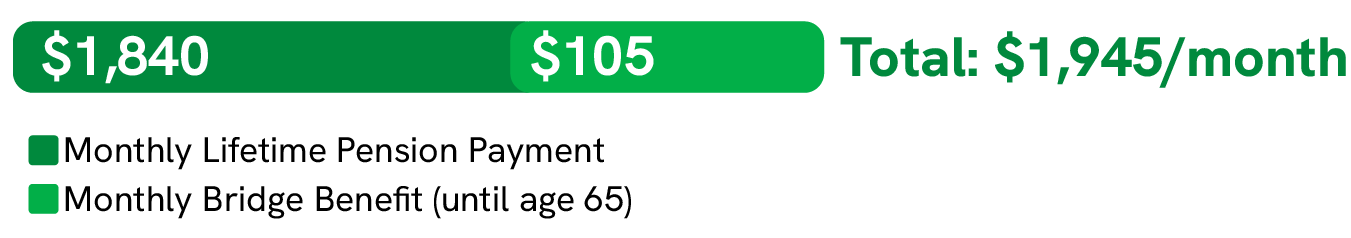
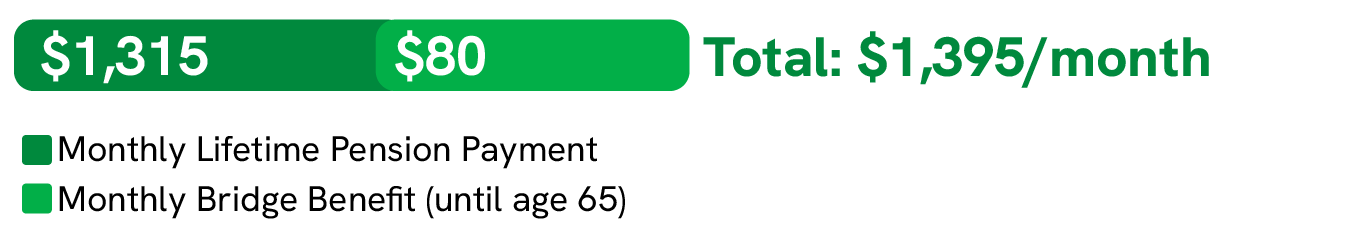
By contributing for these leaves, Lucia will receive on average $535 more per month at retirement and a total of $205,100 more than Michelle between age 55 and age 80. This assumes that their pensions continue to grow during retirement with an annual 2% cost-of-living adjustment, if provided by HOOPP in the future.
Making contributions during her leave helped Lucia increase her pension by adding contributory service. Because Lucia’s contributory leave periods were subject to a past service benefit improvement approved by HOOPP, her pension grew even more.
When it’s time to retire, Lucia is eligible for total HOOPP benefits of $1,945 per month, while Michelle would receive $1,395 per month, which includes a bridge benefit until age 65. That’s a difference of $535 per month or $6,420 per year at retirement!
See what a difference this makes when Lucia and Michelle are 80 years old, in the following tab.
If you do not make contributions on an employer approved leave, you may still be able purchase the service at a later date by completing a buyback. Learn how buying back service can help you maximize your pension.